Allocation Becomes a System
How companies turn economic judgment into P&Ls, ERP rules, attribution models, and auditable software systems.
Alloconomy Foundations — Part 2 of 3
How organizations encode economic judgment
Part 1 defined the anatomy of an allocation: a source pool, targets, a driver, a rule, a boundary, and an authority. Inside an organization, that structure becomes operational.
A company can close its books perfectly and still misunderstand its business.
It may know how much revenue it earned, how much money it spent, how much cash it generated, and how its assets and liabilities changed.
But leaders rarely make decisions only at the consolidated-company level.
They want to know whether a product is profitable.
They want to know whether a country is economically viable.
They want to know whether a customer relationship creates value, whether a delivery promise is sustainable, whether an advertising surface deserves more investment, and whether a business unit is earning an adequate return on capital.
The consolidated ledger cannot answer those questions by itself.
The company must decompose its economics.
That decomposition is an allocation problem.
A P&L Is a Model, Not a Mirror
Some costs can be traced directly.
A physical component installed in a product can usually be associated with that product.
A payment-processing charge can often be connected to a transaction.
A sales commission can be associated with a contract.
Other costs are shared.
A building serves several teams.
A data center supports multiple products.
A transportation network carries packages for many categories, sellers, programs, and countries.
A cybersecurity organization protects the entire enterprise.
A foundational AI model may support search, cloud services, advertising, productivity tools, and products that do not yet exist.
At the consolidated level, the cost is real.
At the product, customer, or business-unit level, ownership of the cost must be modeled.
That distinction is fundamental:
The ledger tells us whether the dollars balance. The allocation model tells us what the dollars mean.
A managerial P&L is therefore not simply discovered inside the accounting records.
It is constructed from observed transactions, attribution models, organizational boundaries, policy choices, and assumptions about economic causality.
This does not mean that a managerial P&L is arbitrary.
A well-designed P&L can provide a rigorous and decision-useful approximation of economic reality.
But its conclusions are only as credible as its boundaries, drivers, assumptions, and controls.
An allocation can be perfectly accurate in aggregate and dangerously misleading in distribution.
Shared Infrastructure Creates Shared Costs
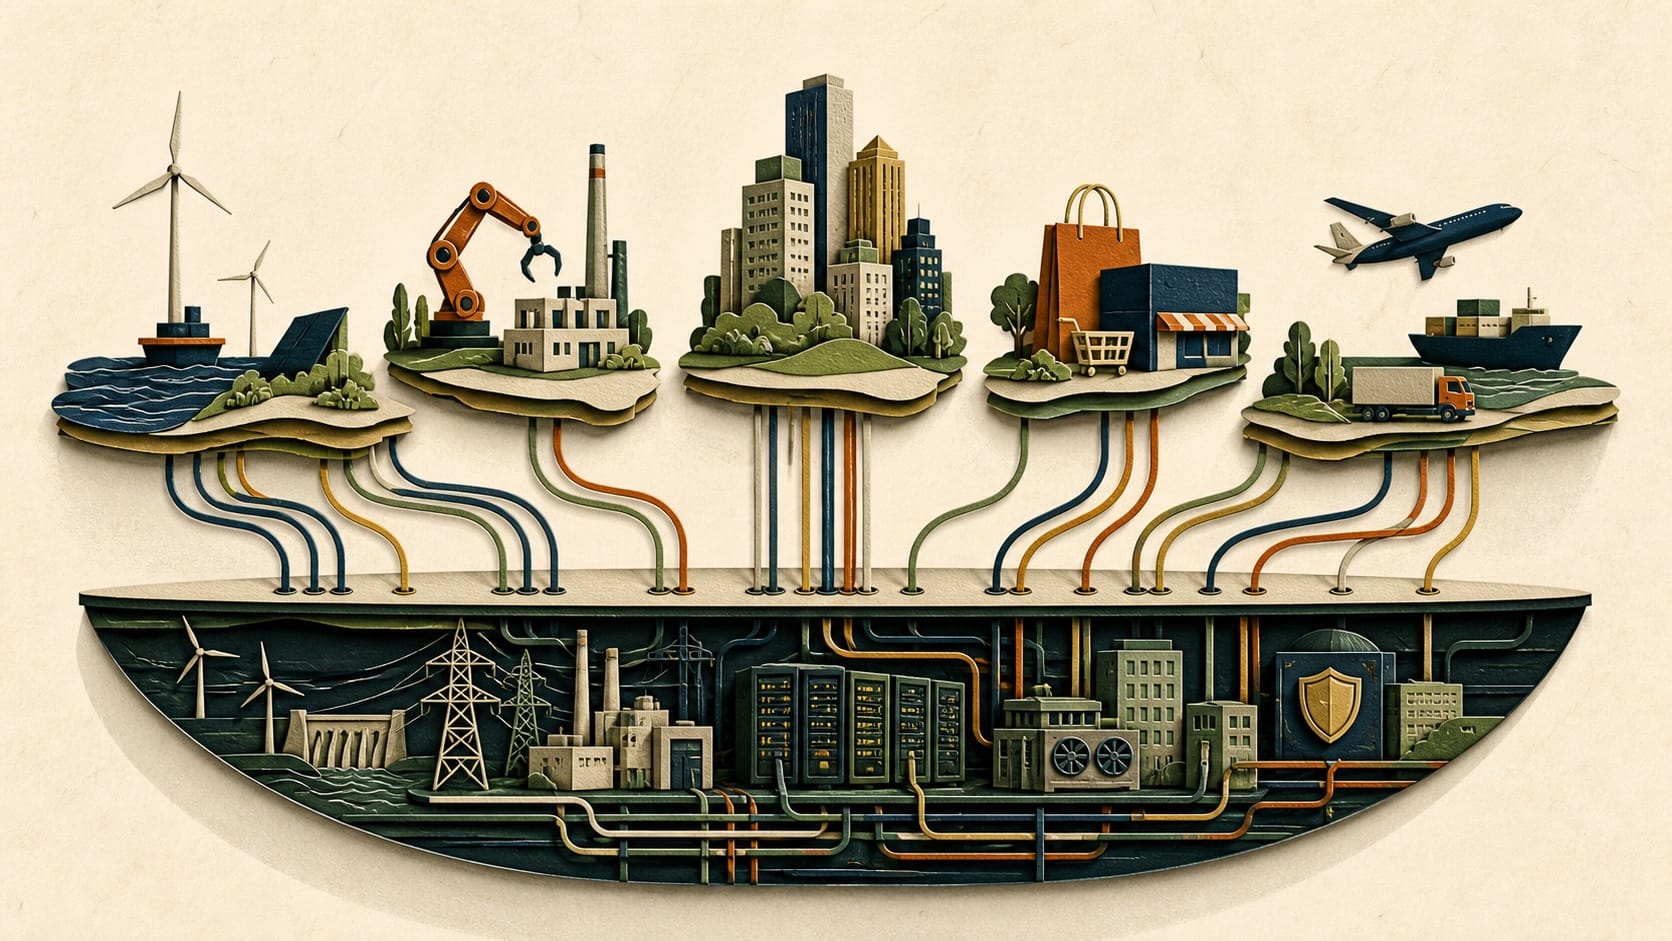
Large platform companies make this problem especially visible because many businesses depend on common infrastructure.
The same shared infrastructure becomes a chain of bottlenecks in the series’ account of how scarcity moves through an interconnected system.
Consider a global commerce and logistics ecosystem such as Amazon.
Amazon’s Pan-European FBA program allows inventory to be sent into its European fulfillment network and then distributed among enabled countries according to anticipated demand. The same wider network of facilities, inventory-placement systems, transportation capacity, and operational software can therefore support several marketplaces rather than belonging neatly to one country or product.
A network of this kind creates many possible shared-cost pools:
- leases, depreciation, electricity, and maintenance for fulfillment and sortation facilities;
- automation and material-handling equipment;
- labor-management and capacity-planning systems;
- transportation capacity across trucks, aircraft, sort centers, and delivery stations;
- customer service, fraud prevention, returns processing, and payment-risk systems;
- identity, security, observability, data, and platform-engineering infrastructure;
- finance, human resources, legal, tax, compliance, and recruiting.
The difficult question is not whether these costs exist.
It is how they should be assigned.
| Shared pool | Plausible drivers | Decision hidden inside “usage” |
|---|---|---|
| Buildings | Square footage, inventory volume, units processed, labor hours | Whether average activity or peak-capacity requirements matter more |
| Transportation | Package count, weight, distance, route time, delivery speed | Whether to charge for observed movement or incremental capacity caused |
| Computing infrastructure | Processor or accelerator time, memory, storage, traffic, power | How to treat reservations, peaks, idle capacity, and future capacity |
| Corporate functions | Headcount, revenue, transactions, legal exposure, security risk | Whether the driver represents service consumed, risk created, or ability to pay |
Each driver can be mathematically coherent.
Each produces a different economic story.
Amazon’s public financial reporting illustrates how significant these choices can become. The company states that technology-infrastructure assets, related additions, and depreciation and amortization are allocated among its segments based on usage, with the majority allocated to AWS. It also notes that usage by the North America and International segments can fluctuate with seasonality, peak periods, and new products or services.
But “usage” is not a self-defining fact.
Someone must decide what counts as usage.
Someone must determine how it will be measured.
Someone must decide how idle capacity, excess capacity, and capacity built for future demand will be treated.
Someone must determine whether peak demand deserves greater weight than average demand.
The accounting disclosure is concise.
The economic model beneath it can be enormous.
Alphabet offers another revealing example.
Its public reporting says that centrally managed expenses such as technical infrastructure and office facilities are generally allocated to operating segments using measures such as usage, headcount, or revenue. But certain costs are intentionally not allocated to the segments. These include some shared AI research and development, corporate initiatives, and selected shared corporate costs. For the quarter ended June 30, 2026, Alphabet reported a $5.789 billion operating loss in “Alphabet-level activities,” primarily reflecting shared AI research and development.
This reveals an important principle:
Choosing not to allocate a cost is itself an allocation policy.
The cost remains at the center, while the operating segments are presented before that shared burden.
That may be appropriate when the benefit is genuinely enterprise-wide, uncertain, long-dated, or impossible to attribute credibly.
But anyone interpreting the resulting segment margins must understand the boundary.
The question is not only:
“Was the allocated cost distributed correctly?”
It is also:
“Which costs were never admitted into the allocation model?”
Revenue Attribution Is the Mirror Image
Companies do not only share costs.
They also share in the creation of revenue.
Amazon’s advertising business demonstrates the scale of the problem.
In the quarter ended June 30, 2026, Amazon reported $19.809 billion of advertising-services revenue, up 26 percent from the corresponding quarter of the previous year. Amazon’s category includes advertising sold through programs such as sponsored ads, display advertising, and video advertising. During the same quarter, Alphabet reported $11.055 billion of YouTube advertising revenue.
The categories are not identical, and the comparison should not be treated as though the businesses were directly interchangeable.
But the scale is instructive.
On this narrow quarterly revenue comparison, Amazon’s reported advertising-services revenue was approximately 1.79 times YouTube’s advertising revenue—about 79 percent larger.
Amazon advertising is not a minor ancillary activity. It is an enormous business.
Yet its economic value is entangled with the rest of the Amazon ecosystem.
The advertising organization may build the auction, campaign tools, targeting systems, measurement capabilities, and ad-serving infrastructure.
But much of what is being monetized is created elsewhere.
Customers arrive because of selection, convenience, pricing, trust, delivery promises, Prime, reviews, product information, and purchase intent.
Sellers and vendors participate because Amazon’s stores attract customers close to making a commercial decision.
Search results and product-detail pages create surfaces on which advertisements can appear.
The fulfillment network helps make advertised products purchasable and deliverable.
Who, then, created the advertising revenue?
Was it the advertising organization that sold and served the advertisement?
Was it the marketplace that assembled customers and sellers?
Was it the search system that produced the relevant impression?
Was it the product-detail page that helped convert attention into intent?
Was it the fulfillment network whose delivery promise made the customer willing to buy?
Was it Prime, which may have increased shopping frequency and engagement?
There is no single inevitable answer.
For statutory accounting, revenue must be recognized according to the applicable accounting rules. The same dollar cannot simply be duplicated across every organization that contributed to creating it.
But managerial economics may require additional views.
A company may want to assign contribution credit.
It may want to compensate business units for the value they enable.
It may want to understand whether one business is economically subsidizing another.
It may want to determine whether advertising is creating incremental purchases or merely monetizing demand that the stores would have generated anyway.
Possible attribution drivers include search-result impressions, product-detail-page views, ad impressions, clicks, attributed purchases, incremental conversion lift, gross profit, advertiser demand, session value, or customer lifetime value.
Once again, the driver is not neutral.
An impression-based model may encourage teams to create more advertising inventory.
A click-based model may reward curiosity rather than economic value.
A last-click model may credit the surface that captured demand while ignoring the systems that created it.
An attributed-sales model may give advertising credit for purchases that would have happened organically.
An incremental-lift model may come closer to causality, but it requires experiments, control groups, counterfactual reasoning, statistical judgment, and acceptance of uncertainty.
Revenue attribution does more than distribute credit.
It influences product placement, organizational power, investment, compensation, and strategic priorities.
What ERP Systems Do
Enterprise-resource-planning systems formalize many allocation decisions.
The terminology differs among vendors, but the basic grammar is remarkably consistent.
The system identifies a source pool.
It identifies eligible targets.
It selects a basis or driver.
It applies an allocation rule.
It creates the resulting accounting entries.
It provides a mechanism to review, balance, and reconcile them.
General Ledger modules can create allocation journals across accounts, entities, departments, and cost centers.
Management Accounting or Controlling modules can perform cost-center distributions, overhead assessments, and activity-based allocations.
Project Costing modules can gather pooled expenses and distribute them among projects and tasks.
Intercompany modules can allocate amounts across legal entities.
Profitability and Performance Management systems can construct views by product, customer, channel, geography, or scenario.
SAP’s Universal Allocation capabilities support the movement of costs and other amounts from sending objects to receiving objects. Oracle Project Costing gathers source amounts into a source pool and distributes them to target projects and tasks using a specified basis method. Microsoft Dynamics 365 supports variable-basis, fixed-percentage, fixed-weight, and equal-distribution methods for ledger allocations.
These systems are not primitive.
They perform critical accounting work with approvals, controls, financial dimensions, and traceability.
They are especially effective when the source amounts are summarized financial balances, the targets are stable accounting dimensions, the rules run periodically, and the desired result is a controlled accounting entry.
ERP systems are designed to close and govern the books.
But modern digital companies increasingly need systems that also explain the operational world behind the books.
When Allocation Becomes a Distributed-Systems Problem
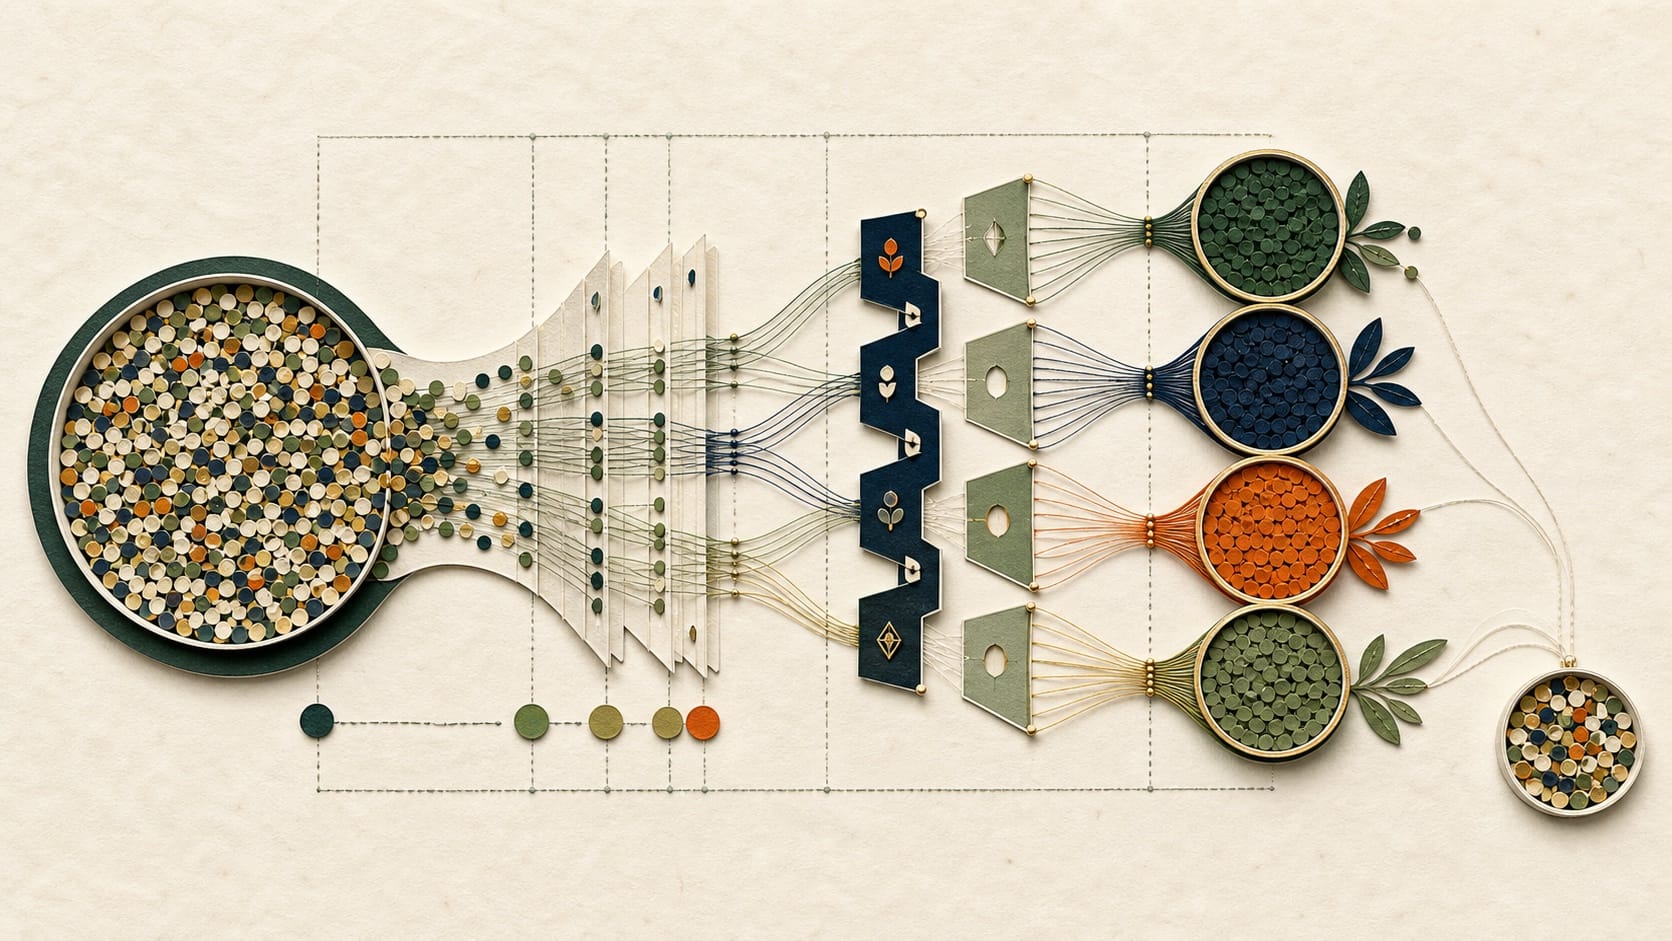
At the simplest level, an allocation is easy to calculate.
The rule is:
Allocation to a target = source pool × that target’s share of the driver.
Suppose a company has $1,000 of shared cost.
Product A represents 20 percent of the selected driver.
Product A receives $200:
$1,000 × 20 percent = $200.
The arithmetic is not the hard part.
The hard part is producing trustworthy values for the source pool, the driver, and the eligible target population—and doing so repeatedly at enormous scale.
In a global digital platform, the source pool may arise from billions of financial and operational events.
The targets may be individual products, orders, shipments, customers, advertisements, sessions, inventory units, contracts, or computing workloads.
The drivers may depend on billions or trillions of impressions, scans, route events, telemetry records, usage measurements, and graph relationships.
The system may need to answer questions such as:
Which inventory cost belongs to which eventual customer shipment?
Which transportation cost was caused by a package, a delivery promise, a route, or capacity reserved for peak demand?
Which advertising revenue was enabled by a search result, marketplace, session, or product-detail page?
Which AI-infrastructure cost belongs to training, inference, experimentation, safety evaluation, reserved capacity, or unused capacity?
Which expense should remain associated with the period in which it was incurred?
Which should be matched to the later activity that consumed or benefited from it?
At that point, the allocation engine is no longer merely a periodic journal generator.
It becomes a versioned, temporal, graph-aware accounting computation.
A robust event-scale system may need to ingest immutable financial and operational events; resolve identities across products, orders, shipments, customers, organizations, accounts, and legal entities; construct source pools without omission or duplication; calculate driver shares; apply exclusions, caps, floors, and multi-stage rules; process reversals and late-arriving data; manage currency conversion and organizational changes; and generate balanced, repeatable outputs.
It must retain lineage from every allocated amount back to the source transaction, driver evidence, rule version, and calculation run.
It must answer more than:
“What number did the system produce?”
It must also answer:
“Why did this target receive this amount?”
“Which source events contributed to it?”
“Which version of the rule was applied?”
“What changed from the previous result?”
“Can the result be reproduced?”
“What amount remained unallocated?”
One basic conservation rule must always hold:
Allocated amount + explicitly unallocated amount = source pool.
Every dollar in the source pool must either reach an eligible target or remain visibly identified as unallocated.
It must not disappear.
It must not be counted twice.
But balancing the pool is only the beginning.
The result must also be complete, explainable, reproducible, timely, decision-useful, and economically defensible.
A scalable allocation platform is not merely a large database aggregation.
It is an economic model with accounting controls, temporal semantics, distributed execution, conservation rules, and auditable lineage.
Fact, Attribution, and Policy Are Different Things
Software can execute an allocation rule.
It cannot independently decide which economic theory that rule should represent.
Should present users pay for infrastructure constructed for future growth?
Should a product that creates customer traffic receive credit for revenue monetized by another product?
Should excess capacity be charged to current businesses, retained centrally, or treated as a strategic investment?
Should shared costs be distributed according to causation, consumption, benefit received, ability to pay, organizational accountability, or long-term strategy?
Should a loss-leading product receive credit for strengthening an ecosystem?
Should a mature business subsidize an emerging one?
These are not implementation details.
They are questions of economics, causality, strategy, governance, and competing ideas of fairness.
A trustworthy system should distinguish three layers.
| Layer | What belongs in it | Example |
|---|---|---|
| Observed fact | Directly traceable transactions, events, obligations, usage measurements, and physical movements | A payment-processing fee associated with a transaction |
| Modeled attribution | An explicit theory of causality, consumption, contribution, or benefit applied to shared economics | A building lease assigned to products according to units processed |
| Policy assignment | Deliberate subsidies, caps, floors, transfers, exceptions, or management decisions | A temporary subsidy granted to a new marketplace |
All three can be legitimate.
The danger appears when they are blended into one number and presented as though every component were an equally objective fact.
When facts, models, and policy choices are collapsed together, organizational politics can masquerade as measurement.
When the layers remain visible, leaders can debate the model honestly.
Bad Allocations Manufacture Bad Decisions
A poorly allocated P&L can make a destructive product appear profitable because its shared costs remain elsewhere.
It can make a valuable platform appear unprofitable because it receives costs without receiving credit for the businesses it enables.
It can encourage a country team to reject a globally valuable investment because the local P&L bears the cost while another region receives the benefit.
It can reward organizations for moving expenses across boundaries rather than eliminating them.
It can cause managers to optimize the driver rather than improve the underlying economics.
It can persuade investors that a business possesses attractive unit economics when important acquisition, infrastructure, support, or corporate costs have been excluded.
It can move capital away from businesses that create long-term optionality and toward businesses that merely look attractive within the current allocation boundary.
Allocation systems are therefore systems of organizational governance.
They define accountability.
They distribute power.
They influence investment, compensation, hiring, pricing, product design, and promotion decisions.
A bad allocation system does not merely misstate economic truth.
It manufactures bad decisions.
And decisions about capital, talent, infrastructure, and research determine which future capabilities are created—and which never come into existence.
A P&L is not merely a retrospective statement about the past.
It becomes an input into future capital allocation.
If the economic model is wrong, resources move toward the wrong constraints.
If the model is sound, organizations can direct capital, talent, and attention toward the bottlenecks that most limit future capability.
That is where allocation connects to abundance.
Continue the reading path
Previous — Part 1: ← Allocation Is Life
Next — Part 3: Abundance Is an Allocation Problem →