Airbnb: A Booking Has More Than One Clock
Separate booking, cash, check-in, payout, and later service adjustments.
Who this is for. You should already recognize the P&L (income statement), balance sheet, cash flow statement, accounting equation, and double-entry bookkeeping. You do not need to be an accounting specialist. For a refresher, start with James Hearle’s Accounting Stuff accounting-equation refresher, then return to the worked example.
Public sources and fictional examples. Company-specific facts come only from cited public materials. Every scenario, workflow, cutoff, rate, volume, allocation, and profitability amount is invented for teaching and must not be read as a description of any company’s internal practice. The interpretations are my own and do not represent my employer or any other organization. No confidential, proprietary, or nonpublic information is used.
For the foundation, read the series introduction and Monthly Close.
One reservation travels through several dates
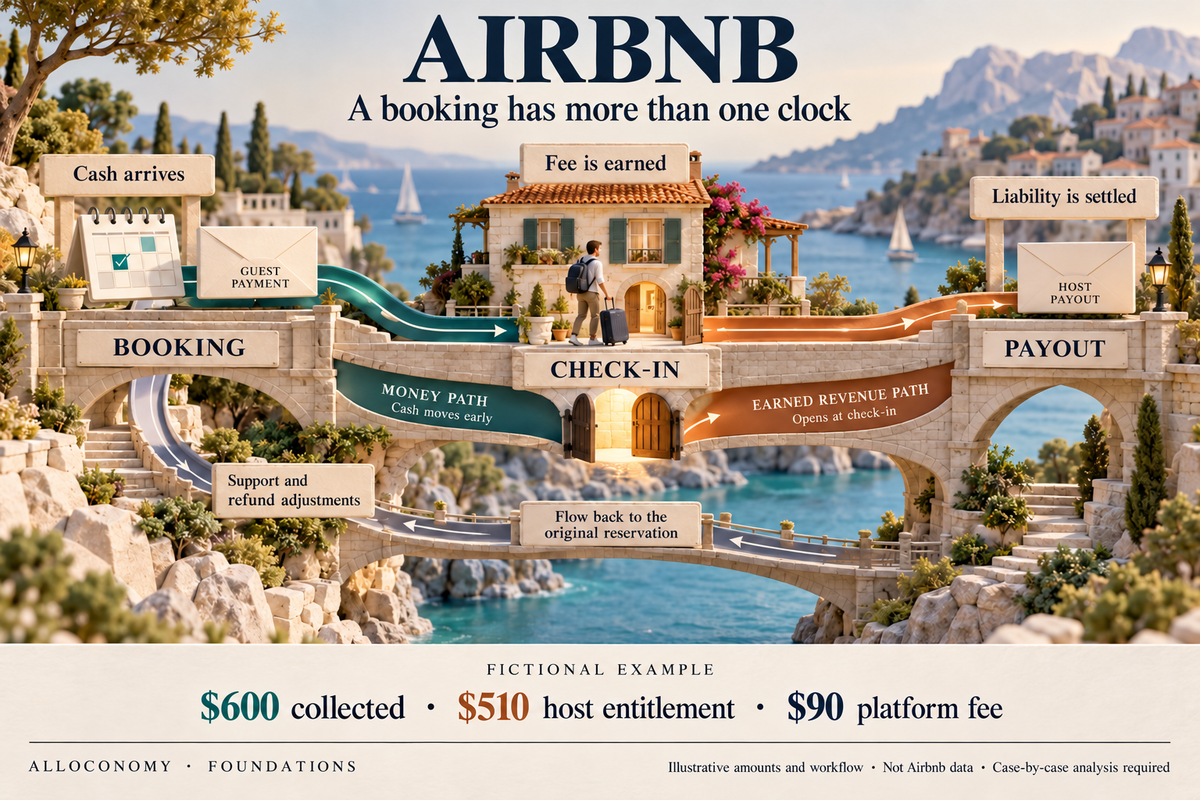
Consider a fictional three-night reservation booked on October 20, checking in on October 28. The guest pays $600. Our simplified host-fee model assigns $510 to the host and $90 to the platform. These are invented amounts, not a quoted Airbnb fee schedule. We omit taxes, currency conversion, installment payments, and long stays.
Airbnb’s disclosure says revenue from a short stay is recognized at check-in, while service fees collected beforehand are recorded as unearned fees. The accommodation value and the platform’s revenue are different amounts. Airbnb 2025 annual report, revenue recognition.
Our unit is the reservation. We also retain service dates and booking dates so that a reservation-lifetime view can be reconciled to daily and monthly accounting. Spreading the $90 evenly across the three nights would be an analytical allocation, not the disclosed check-in recognition rule for this example.
Booking day brings cash and obligations
On October 20, the teaching model records $600 of cash or processor receivable, $510 owed for onward settlement, and $90 of unearned platform fees. No platform revenue is earned yet under the assumed check-in policy.
Assume the processor charges $18 at collection and that this cost is expensed on that date. If settlement is net, the bank receives $582. Gross records still preserve the $600 collection and the $18 fee. Cash settlement is not a second booking.
The reservation now has −$18 of cumulative contribution, with its service still ahead. A projected lifetime margin may be useful, but it must be labeled a forecast rather than earned profit.
This early negative result is a timing fact. It does not by itself establish that accepting the reservation was a bad decision.
Check-in changes what has been earned
The October 28 daily run selects reservations that reached check-in by the specified local cutoff, using evidence received by 06:00 the following morning. Cancellations and modified reservations require separate status checks. A revised itinerary must not leave both the old and new versions earning revenue.
For the worked reservation, the $90 moves from unearned fees to earned platform revenue. We assume no host payout has yet occurred; the $510 obligation remains payable. Paying it tomorrow will clear the liability without reducing the $90 revenue again.
The close also includes $6 of support activity, a $4 expected platform-fee refund, and $2 of expected third-party service-resolution work paid by the platform. The $4 is modeled as a reduction of revenue; the $2 is a separate cost pool for third-party work, excluding guest or host refunds and credits and with no overlap with support. These are case assumptions requiring a real company to establish its own accounting treatment and evidence.
| Reservation view at check-in | USD |
|---|---|
| Gross platform fee earned | 90.00 |
| Expected platform-fee refund | −4.00 |
| Net revenue | 86.00 |
| Payment fee incurred on booking day | −18.00 |
| Support activity | −6.00 |
| Expected service-resolution cost | −2.00 |
| Cumulative reservation contribution | 60.00 |
The $600 collected never appears as platform revenue in this net teaching model.
A lifetime result and a daily result can both be right
October 20 recorded −$18. October 28 adds $90 − $4 − $6 − $2 = $78. Together they produce the $60 cumulative contribution.
Reporting $60 as the October 28 accounting result would silently move the earlier $18 expense into the wrong day. Reporting $78 as the reservation’s lifetime contribution would omit that expense.
The daily unit close therefore needs two connected views: what changed today and what this reservation has earned and consumed to date. If booking and check-in cross month-end, that distinction becomes essential to the monthly reconciliation.
The operating model may use lifetime economics to compare reservations. The ledger preserves recognition by period. A bridge explains their timing differences.
Replace estimates when the resolution arrives
Later, the processor fee is confirmed as $18.50. Additional support increases total support cost to $9. A fee refund is resolved at $7 instead of the $4 estimated. The separate service-resolution estimate stays at $2.
Updated net revenue is $90 − $7 = $83. Updated included costs are $18.50 + $9 + $2 = $29.50. Updated cumulative contribution is $53.50.
| Change from the daily view | Contribution effect |
|---|---|
| Payment fee increases by $0.50 | −$0.50 |
| Support increases by $3 | −$3.00 |
| Refund increases from $4 to $7 | −$3.00 |
| Total revision | −$6.50 |
The history now reconciles: −$18 + $78 − $6.50 = $53.50.
The $7 refund settles the $4 estimated refund obligation and adds a $3 reduction in revenue under our assumption. It is not a $7 new revenue reduction while leaving the earlier $4 deduction untouched.
What the daily team must reconcile
The reservation identifier connects itinerary versions, collections, check-in evidence, payout instructions, support records, and refunds. The team compares the check-in population to recognized fees, collections to processor records, host obligations to settlements, and estimate pools to the relevant accounting balances.
A booking with missing check-in evidence remains an exception with a defined policy and owner. The system should not assume that a scheduled date proves the stay began, nor should it silently omit the reservation from every completeness report.
Changes must distinguish late evidence from a correction to a faulty rule. The former may update one reservation; the latter may require controlled recomputation of a whole affected population. Accounting determines whether an adjustment belongs in an open period or requires other treatment; an analytics refresh does not silently reopen the general ledger.
What the decision changes
A marketing team comparing booking cohorts needs acquisition spending, cancellations, and completed stays over an appropriate horizon. A service team comparing difficult stays needs support and resolution costs attached to the correct reservations. An accountant needs period recognition, even when a cohort chart tells a different timing story.
A large cash collection is not proof of a profitable day. A reservation with high gross accommodation value does not automatically generate high platform contribution. And an apparently strong check-in cohort can still be missing costs incurred before arrival.
Remember the crux: one reservation has several clocks. The daily close connects them without forcing booking, cash, revenue, and payout into the same date.